SDAudit Services
Loan Types We Audit
Explore the loan categories we review and the records typically included in each audit.
What Changes From One Loan Type to Another
The underlying question is the same for every loan we review: what do the records actually show about how this debt was created, serviced, and transferred? What changes is where those records live, and how much of the trail is public.
That distinction matters more than most borrowers expect, because it determines how much an audit can establish.
- Mortgages leave the deepest public trail. Assignments are recorded at the county. Trusts file their governing documents with the SEC. MERS registration is publicly searchable. A mortgage review can often reconstruct the full ownership chain from records you could pull yourself.
- Auto loans leave a shallower one. There is no county recording of an auto loan transfer. Perfection runs through the title and, for commercial arrangements, UCC filings. Securitization happens, but the loan-level detail in public filings is thinner.
- Student loans vary enormously. Private loans are frequently securitized and transferred repeatedly. Federal loans operate under an entirely different framework and are generally not reviewed this way.
- Credit cards are sold in portfolios, not individually. That changes what a chain-of-ownership review can prove — the relevant documents are bills of sale and account-level records rather than recorded assignments.
We will tell you before you order if your loan type limits what the review can reach. There is no point selling a securitization audit on a loan that was never securitized.
Loan Types We Audit
Our team provides detailed audit services across the major loan categories below. Each review is tailored to the documents, records, and concerns connected to the loan.
Mortgage Loans
Analysis of residential and commercial mortgage records for securitization issues, chain-of-title concerns, and compliance questions.
- Trust identification and verification
- Assignment chain analysis
- Note endorsement validation
- Foreclosure standing assessment
- Regulatory compliance review
Auto Loans
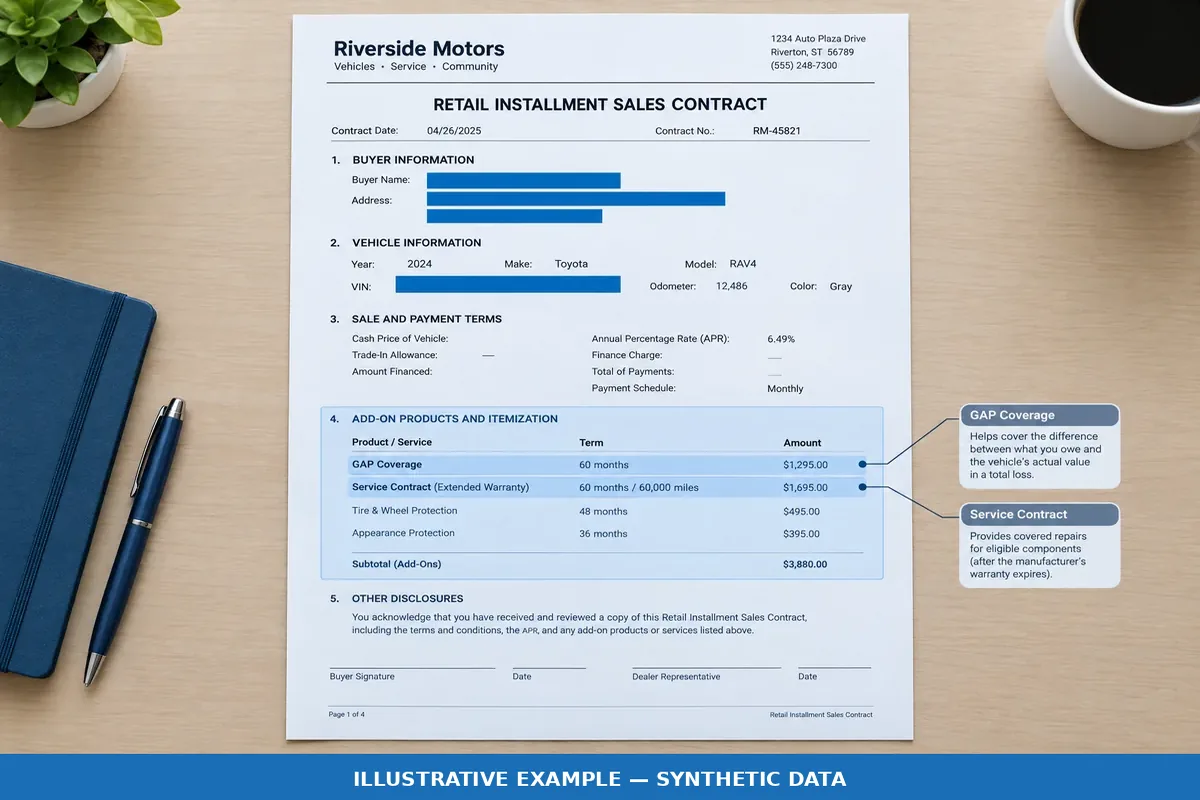
Examination of auto loan documentation to identify fee, interest-calculation, disclosure, and securitization concerns.
- GAP insurance verification
- Interest calculation review
- Add-on product assessment
- Securitization verification
- Repossession practice evaluation
Credit Cards
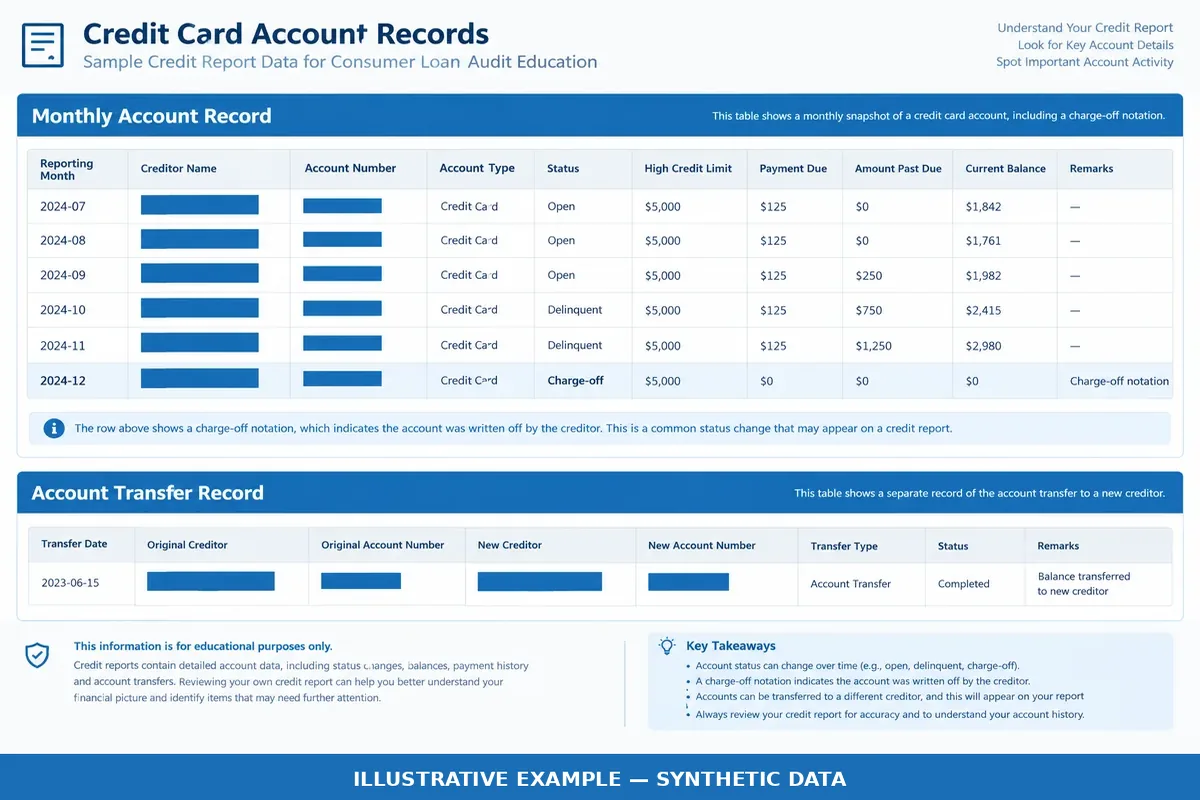
Review of credit-card agreements and account administration for interest, fee, payment, and collection issues.
- Interest rate compliance check
- Fee structure analysis
- Payment application review
- Debt sale verification
- Collection practice assessment
Student Loans
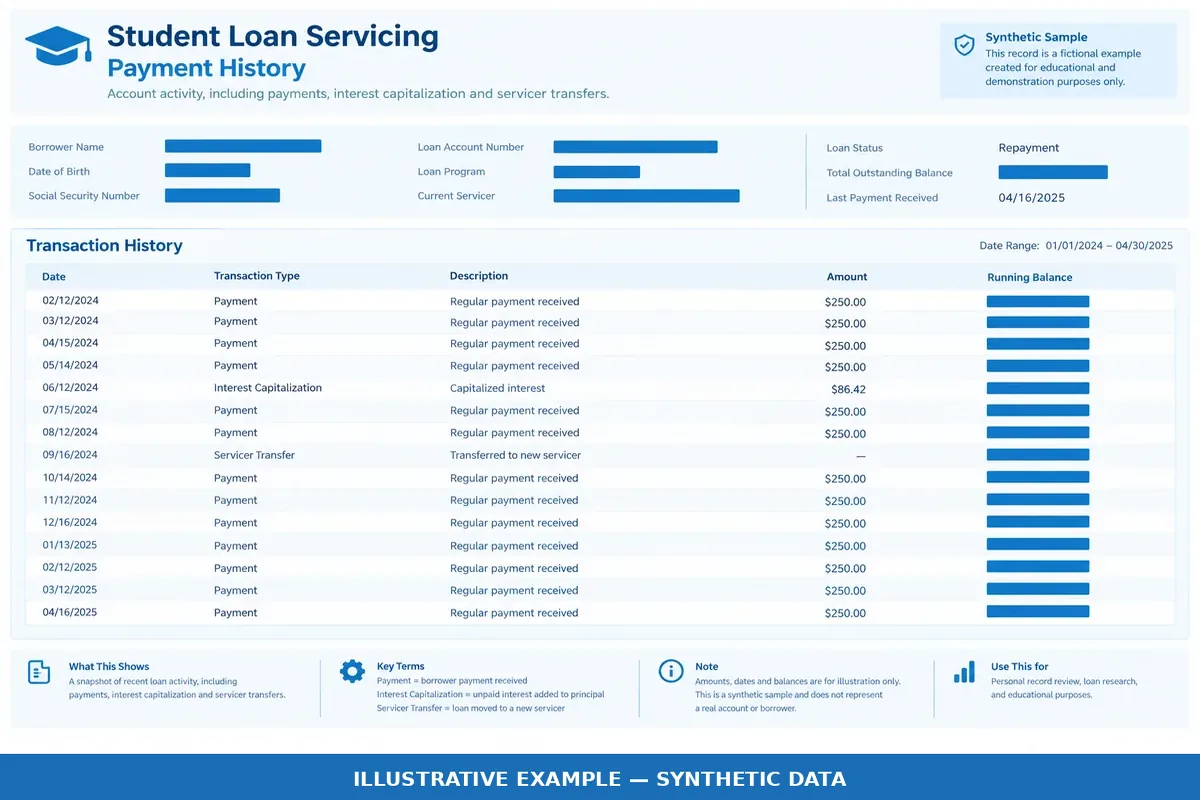
Review of student loan documentation, servicing history, and regulatory compliance records.
- Servicing transfer validation
- Payment application verification
- Interest calculation review
- Deferment and forbearance analysis
- Federal loan compliance check
Consumer Loans
Analysis of personal loans, payday loans, and other consumer credit documentation.
- Truth in Lending compliance
- Fee structure analysis
- Interest calculation verification
- Ability-to-repay documentation review
- Collection practice review
Business Loans
Examination of business loans, credit lines, and commercial financing documentation.
- Term compliance review
- Fee structure analysis
- Securitization verification
- Covenant assessment
- Collection practice evaluation
Records Typically Available by Loan Type
Mortgage loans
Residential and commercial. The most complete review available, because the documentation requirements are the most formal and most of the trail is public record.
- The note and any allonges, showing endorsements between holders.
- The deed of trust or mortgage, and whether MERS appears as nominee.
- Recorded assignments from the county recorder, with dates and signing officers.
- Trust documents filed with the SEC, including the Pooling and Servicing Agreement and its stated cutoff date.
- The servicing and payment history, escrow analyses, and any fee assessments.
- Closing disclosures, measured against Regulation Z and Regulation X requirements.
Reviewed in depth on the forensic mortgage audit and securitization audit pages.
Auto loans
Retail installment contracts from dealerships, and direct auto lending. The origination documents are usually where the substance is.
- The retail installment sales contract and the buyer’s order, compared line by line.
- Add-on products — GAP coverage, service contracts, protection packages — and whether the charges match what was presented.
- The amount financed and finance charge, reconciled against the disclosed APR.
- Title records showing the lienholder of record.
- UCC-1 and UCC-3 filings where the loan was assigned commercially.
- Servicing records, including fee assessments and any repossession accounting.
Covered in detail in the auto loan audit guide.
Student loans
Private student loans only. Federal loans are administered under the Higher Education Act and a separate servicing framework; a securitization-style review does not apply to them in the same way.
- The promissory note and disclosure statements.
- Servicing transfer notices, which on private student debt can be numerous.
- Payment application records and interest capitalization events.
- Deferment and forbearance records, and how interest accrued during each.
- Trust documents where the loan was pooled into a student loan asset-backed security.
Credit cards
Reviewed at the account level. Because card receivables are sold in bulk portfolios, the question is less “who holds this specific account” and more “what documentation supports the balance and the transfer.”
- The cardmember agreement in effect, and any change-in-terms notices.
- Statement history, showing interest applied and fees assessed.
- Payment allocation, measured against the CARD Act’s ordering requirements.
- Charge-off notation and the date it occurred.
- Bill of sale and account schedule where the debt was sold to a purchaser.
Personal and consumer installment loans
Includes personal loans, point-of-sale financing, and short-term consumer credit. What is available varies widely by originator.
- The loan agreement and Truth in Lending disclosure.
- Fee schedule and how fees were actually assessed against the account.
- Interest calculation method and whether it matches the disclosed terms.
- Any assignment or sale documentation.
- Collection account records where the debt has been placed or sold.
Business and commercial loans
Term loans, credit lines, and equipment financing. Consumer protection statutes largely do not apply here, so the review centers on the contract itself and the security interest.
- The loan agreement, note, and any personal guaranty.
- Covenant terms and the documented basis for any declared default.
- UCC-1 filings and continuation statements establishing perfection under Article 9.
- Fee and interest calculation measured against the stated terms.
- Assignment or participation documentation where the loan was sold.
Choosing the Right Review
Three questions usually settle it:
- What are you actually trying to find out? If the question is “who owns this debt,” you want a transfer-focused review. If it is “were the terms disclosed correctly” or “has my account been handled properly,” you want an origination and servicing review.
- What documents do you have? The review goes further with a complete file. If you are missing most of it, start by requesting records from your servicer before ordering.
- Is there a deadline? If there is active litigation or a foreclosure timeline, tell us when you call. It changes which package makes sense and whether the turnaround works.
Package scope and flat-rate pricing for each loan type are on the pricing page. If you are not sure which fits, call 888-450-4221 and describe the situation — we would rather point you to the right review, or tell you none of them fits, than sell you the wrong one.
SDAudit prepares document analysis. We are not attorneys, we do not provide legal advice or representation, and no audit guarantees any particular outcome.
Ready to audit your loan?
Start with the audit package that fits your loan type and the records you need reviewed.